EMEA personal care and cleaning chemicals market is forecast to reach $25 billion by 2024
EMEA personal care and cleaning chemicals market is forecast to reach $25 billion by 2024, after growing at a CAGR of 5% during 2019-2024. The growth of EMEA personal care and cleaning chemicals market is mainly driven the increasing initiatives by industry players to enhance the existing products through Research and Development (R&D). Apart from that, the growing demand for halal products, climate conditions, and growing population in Middle and Africa are also playing a pivotal role in supporting the growth of EMEA personal care and cleaning chemicals market.
Report Coverage
The report: “EMEA Personal Care and Cleaning Chemicals Market– Forecast (2019-2024)”, by IndustryARC, covers an in-depth analysis of the following segments of the EMEA Personal Care and Cleaning Chemicals Market.
Request Sample
Key Takeaways
· Europe dominates the EMEA personal care and cleaning chemicals market. European cosmetics, especially the branded products with the designer labels, are considered as high-end products in the global market. The German personal care and cleaning chemicals market accounted for the highest revenue share in 2017.
· The increasing demand for personal care chemicals, supported by the rising consumer awareness towards ingredients and the rising middle class with higher disposable income, is fueling the demand for surfactants.
· The demand for cleaning products is mainly driven by the more demanding lifestyles of people that require cleaning products, which are efficient and requires less time to clean things.
Type - Segment Analysis
Surfactants hold the largest market share of the EMEA personal care and cleaning chemicals market in 2018, followed by esters segment; while mild surfactants are expected to witness the highest growth rate during the forecast period. The growing demand for personal care products, supported by increasing household disposable income, has played a significant role in increasing the demand for surfactants. The personal care industry use amphoteric surfactants owing to its mild and skin-friendly features. Further, in 2017, the Organization for Economic Co-operation and Development (OECD) reported a 3.5% year on year (y-o-y) growth in the European Union’s household disposable income.
Application- Segment Analysis
Cleaning segment held the largest share in EMEA personal care and cleaning chemicals market in 2018, followed by personal care segment; while the personal care segment is expected to witness the highest growth rate during the forecast period. The personal care industry will remain the most attractive market for Europe chemical manufacturers in the forecast period.
Consumers are getting more aware of the organic and natural care products, around 80% the demand from Spain is driven by natural products, which were not tested on animals. The growing consumer demand for organic and natural care products has actuated many industry players to change their planning their production and R&D activities per their customer’s viewpoint.
Geography - Segment Analysis
Europe dominated the EMEA personal care and cleaning chemicals market with a share of 80%, followed by the Middle East and Africa. The growth of personal care and cleaning chemicals market in the European market is mainly driven by growing domestic demand for personal care and cleaning products. In the last few years, Germany has emerged as a major market for cosmetics; while the UK held in the largest share in European sun care products.
In European cleanings products market, household cleaning chemicals held the largest share while Industrial & Institutional segment holds the remaining share. The demand for household cleaning chemicals is mostly driven by the growing utilization of laundry detergents in household laundry activities. The increasing adoption of automated washing machine has boosted the demand for laundry detergent in millions of households around Europe.
Owing to its large consumer base and steady beauty care market, Germany continues to dominate the European personal care and cleaning chemicals market. In 2017, Germany had around 82 million consumers that played a key role in supporting the growth of personal care and cleaning chemicals market. Further, in 2017, the German Cosmetic, Toiletry, Perfumery, and Detergent Association (IKW) reported a 0.5 % y-o-y growth for the beauty care market.
Drivers – EMEA Personal Care and Cleaning Chemicals
· Product enhancement through R&D and focus on consumer safety in Europe cosmetic industry
The growing R&D investment mainly drives the cosmetics and personal care industry for product development and enhancement. In 2018, Cosmetic Europe reported that Europe has at least 77 innovation facilities that research cosmetics. Scientists in Europe are developing cosmetic products by reformulations and the adoption of modern procedures. European Scientists are using materials at a molecular level to develop whole new generation products, not only for cosmetic products such as sun creams but also medicines, electronics, and telecoms.
The European Union Cosmetics Regulation is another factor driving the market as it regulates the safety of cosmetics for consumers through rigorous science-based regulations. The European consumers are concerned about the quality, safety, and organic content in personal care products which has made the European Union Cosmetics Regulation body to draft the safety rules under Regulation (EC) No. 1223/2009 to fulfill the need and demand of consumer preference.
· Demand for Halal products, climate conditions, and growing population in MEA region
The cosmetics industry in the Middle East and some part of the African region are focusing on producing Halal personal care products which meet the criteria according to the Islamic faith. The increase in population has escalated the demand for personal care products across the MEA region. With the growing population, more youngsters, including men and women’s are taking up personal care as their daily requirement, need to look better or beautiful.
The Halal products comply with the Islamic faith and reassure Muslim consumers that the products they use are natural, pure, and hygienically manufactured, and animal-cruelty free. The rise of halal category comes hand in hand with the rising segment of the young population keen to combine religious observance with an emphasis on fashion and beauty in the Middle East. Women who wear hijab often need targeted scalp care and hair products, and for men, beard oils and skin balm are popular.
The middle-class population in Africa has a triple fold in the last few decades, and modernization of many African countries has attracted the attention of big cosmetics groups to invest in personal care and cosmetic products.
Schedule a Call
Challenges – EMEA Personal Care and Cleaning Chemicals
· Regulatory challenges from government regulation body
Various regulations related to the usage of certain chemicals in personal care and cleaning products has emerged as a significant challenges beauty industry in Europe, Middle East, and Africa. In Europe, the beauty industry is facing challenges with regulations related to harmonizing the interpretation of the procedure of banning Carcinogenic, mutagenic, reprotoxic (CMR) substances. The EU Cosmetics Regulation 1223/2009 contains provisions on the use of CMR in cosmetic products.
The regulatory standard gives assurance to the consumers that a product is safe and of good quality. In Africa, countries such as South Africa is generally a self-regulated, and firms are still required to comply with certain standards such as Good Manufacturing Practice (GMP), which is costly. Currently, South African Bureau of Standards (SABS) does not offer this service and firms can only opt to private testing making it relatively expensive, but these regulations are not necessarily prohibitive for smaller players looking to access the mass market which in thus raises the concern among consumers for homemade products.
The members of the Gulf Cooperation Council have sophisticated chemical control regulations throughout the Middle East. They have a strict policy towards the consumer goods in chemical and personal care industry following the international market standards which sets a regulatory barrier for local manufacturers to penetrate or come in the market without having accreditation from well known regulatory bodies cited according to international standards.
· Economic stress and geopolitical tension in the MEA region
The growth in the region can be achieved directly when the region is stable from inside in terms of economic growth and per capita income. The personal care and cleaning chemicals industry’s sales growth rates in the Middle East and some part of Africa has been slow in few years as the region grapples with, international trade regulations and rising geopolitical tensions.
All these factors are directly affecting the buyers buying power as it is crippling the economy, which is affecting the per capita income of the region. Further, it is directly affecting the FDI in the country’s small macro industries for producing commodities according to international standards. A plunge in the Egyptian currency was seen, and Saudi Arabia has reduced dependency on government subsidies, hitting consumer spending.
The unbalance in some parts of African countries such as Zambia has seen a decrease in sustainable economic growth and employment creation, which has affected the spending capabilities of consumers.
South Africa has experienced a premature decline in employment rate and production of the commodity. According to Trade and Industrial Policy Strategies Forum 2017, trade data shows that there is a trade deficit of $536 million for cosmetics and $667 million for soaps and detergents in South African Development Community (SADC) region.
Buy Now
Market Landscape
Product launches, merger & acquisitions, and R&D activities are key strategies adopted by players in the EMEA personal care and cleaning chemicals. In 2018, the market of EMEA personal care and cleaning chemicals had been consolidated by the top five players accounting for xx% of the share. Major players in the EMEA personal care and cleaning chemicals are BASF SE, DowDuPont Inc., Solvay SA, Evonik Industries, AkzoNobel N.V., Symrise AG, Lanxess AG, and Ashland Global Holdings Inc. among others.
We also publish more than 100 reports every month in “Chemicals and Materials”, Go through the Domain if there are any other areas for which you would like to get a market research study.
Propylene Glycol Market - Forecast(2020 - 2025)
Propylene glycol, also identified as propane 1, 2-diol according to International Union of Pure and Applied Chemistry nomenclature, is a synthetic organic compound. It is produced from petroleum products as well as it is bio-based and equipped with certain peculiar traits such as outstanding stability, high flash and boiling point, as well as low vapor pressure and broad solvency.
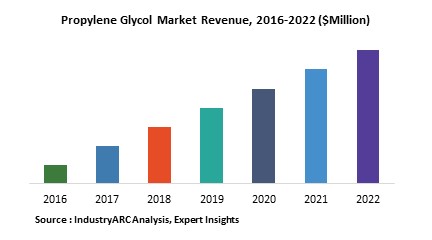
Owing to such characteristics it has found tremendous scope of industrial application to craft products such as unsaturated polyester resin, coolants and antifreeze, hydraulic and brake fluid, aircraft deicing fluid, and paints and coatings. The analyst in this research report has stated the global propylene market size to be valued at around $3655 million as of 2018 and is estimated to be growing at a CAGR of around3.9% during the forecast period of 2019-2025.
Request Sample
Global Propylene Glycol Market Outlook:
Propylene Glycol is segmented into two grades mainly industrial and pharmaceuticals. Owing to such deliverance of variants it catches wide applications in countless end-use industries with construction and infrastructure, automotive, aerospace, chemical, household, packaging, food & beverages, pharmaceutical, cosmetics and personal care being the major arcades effecting the global propylene glycol market demand.
After an acute analysis of the regional market outlook, APAC region is reckoned to be dominating the global propylene glycol market size by encapsulating more than 32% of the global demand under its own territory. Such dominance can be attributed to the epidemic growth of the Indian and Chinese automotive, construction, F&B, and pharmaceutical sectors catering to nearly half of the global population hosted by these two economies. As per the Open Government Data Platform India latest data records, the total vehicle population in India 2015 was 210 million and the sector is rapidly expanding (5.83%, 2017, OICA), thus the automotive sector being a major employer of propylene glycol as coolants and antifreeze and hydraulic and brake fluid is all set to stroke the market with abundant demand.
Global construction market is forecast to grow by $8 trillion by 2030 driven by China, US and India. Unsaturated polyester resins derived from propylene glycol are reinforced with fiber glass to form fiber glass reinforced plastics (FRPs), which has found tremendous employment in crafting building panels, bathroom components, fixtures and corrosion-resistant tanks, pipes, electrical components, paints and ducts in the building and construction sector. Due such extensive scope of application, building and construction sector is leading the application segment and is forecast to grow at a CAGR of around 3.9% going through 2025.
Inquiry Before Buying
Global Propylene Glycol Market Growth Drivers and Trends:
Deicing and anti-icing fluids performs a vital operation in providing safe, uninterrupted and timely air travel during extreme winter conditions. Federal Aviation Administration “Clean Aircraft Concept,” outlaws takeoff with ice contamination on critical surfaces of an airplane. Thus the replacement of ethylene glycol by propylene glycol as the base fluid for aircraft deicing formulations is driving the market towards abundant opportunities of application. Furthermore, cumulative amount of space exploration agendas amalgamated with the ultimatum for high quality antifreeze & coolant is estimated to raise the demand for bio based propylene glycol
According to a 2017 report by Forbes, the top 25 companies in the F&B sector generated $741.2 billion in revenue in 2016 and $86 billion in profit. Another considerable data from Committee for Economic Development states that the food sector accounts for about 5 percent of US GDP and 10 percent of US consumers disposable personal income (DPI)[4]. Now owing to the trend of convenience packaged food for longer shelf life, the employment of propylene glycol as food additives is driving the market and is all set to divert a hefty revenue from the flourishing F&B sector into its own returns pocket.
Global Propylene Glycol Market Challenges:
Health problems concerning to propylene glycol is the major challenge encountered by propylene glycol manufacturers. There are several health distresses accompanying propylene glycol that can adversely affect the market growth. However, FDA classifies propylene glycol as an additive that is generally recognized as safe for use in food. Similarly, WHO has specified that the acceptable daily intake of propylene glycol as a food additive should exceed more than 25 mg/ Kilogram of weight.
According to a 2017 report by Forbes, the top 25 companies in the F&B sector generated $741.2 billion in revenue in 2016 and $86 billion in profit. Another considerable data from Committee for Economic Development states that the food sector accounts for about 5 percent of US GDP and 10 percent of US consumers disposable personal income (DPI)[4]. Now owing to the trend of convenience packaged food for longer shelf life, the employment of propylene glycol as food additives is driving the market and is all set to divert a hefty revenue from the flourishing F&B sector into its own returns pocket.
Global Propylene Glycol Market Challenges:
Health problems concerning to propylene glycol is the major challenge encountered by propylene glycol manufacturers. There are several health distresses accompanying propylene glycol that can adversely affect the market growth. However, FDA classifies propylene glycol as an additive that is generally recognized as safe for use in food. Similarly, WHO has specified that the acceptable daily intake of propylene glycol as a food additive should exceed more than 25 mg/ Kilogram of weight.
Schedule a Call
Global Propylene Glycol Market Players Perspective:
Some of the key players profiled in this business intelligence report are The Dow Chemical Company, LyondellBasell Industries N.V., BASF SE, Archer Daniels Midland Company, Global Bio-chem Technology Group Co., Ltd., DuPont Tate & Lyle Bio Products Company, LLC, Huntsman Corporation and SKC Co., Ltd.
The Dow Chemical Company is a significant producer of propylene glycols since 1948. It offers industrial PG grades for industrial applications and specialty PG grades for the employment in subtle and sensitive applications such as pharmaceuticals, F&B, personal care or animal fodder. This flexibility combined with quality control in manufacture, an extensive delivery network and committed client service make propylene glycols from Dow broadly acknowledged and favored by industries.
Global Propylene Glycol Market Research Scope:
The base year of the study is 2018, with forecast done up to 2025. The study presents a thorough analysis of the competitive landscape, taking into account the market shares of the leading companies. It also provides information on unit shipments. These provide the key market participants with the necessary business intelligence and help them understand the future of the Global Propylene Glycol Market. The assessment includes the forecast, an overview of the competitive structure, the market shares of the competitors, as well as the market trends, market demands, market drivers, market challenges, and product analysis.
Buy Now
The market drivers and restraints have been assessed to fathom their impact over the forecast period. This report further identifies the key opportunities for growth while also detailing the key challenges and possible threats. The key areas of focus include the types of grades in the Global Propylene Glycol Market, and their specific applications in different phases of operations.
The market drivers and restraints have been assessed to fathom their impact over the forecast period. This report further identifies the key opportunities for growth while also detailing the key challenges and possible threats. The key areas of focus include the types of grades in the Global Propylene Glycol Market, and their specific applications in different phases of operations.
- We also publish more than 100 reports every month in “Chemicals and Materials”, Go through the Domain if there are any other areas for which you would like to get a market research study.
Plasterboard Market - Forecast(2020 - 2025)
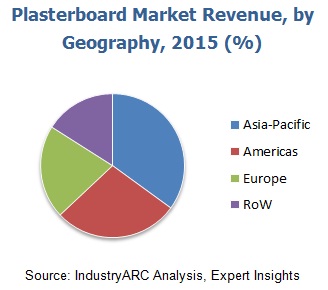
According to Eurogypsum, more than 1,600 million square meters of interior surfaces are covered with plasterboards with around 5 million tons of plaster used for interior lining in Europe each year Similarly, owing to the on-going construction and intermittent replacement of the old plasterboards with the new ones across the globe, the plasterboard market has attained a permanent demand influx from various sectors, and its market size was $19,754 million in 2018, according to the findings by IndustryARC’s market analyst. Furthermore, the analyst estimates the demand for plasterboard to grow with a modest CAGR of 4.6% during the forecast period of 2019 to 2025.
According to the United Nations ESCAP (UNESCAP), in 2013, 60% of the world’s population was attributed to APAC which translates to a whopping 4.3 billion. Even though the organization estimates that the population will observe a growth rate of 0.96% year on year, the population will shoot up to around 5 billion in 2050. Now, this gradual population growth is stirring the construction industry, which is creating a major plasterboard marketplace in the APAC region which held the maximum global market share of more than 36% in 2018, according to the market expert.
Request Sample
Plasterboard Market Outlook:
Plasterboard, also known as drywall, wallboard, sheet rock, gyprock, gypsum board, and gypsum panel is a panel made of calcium sulfate dehydrate (dehydrate). It is widely used in walls and ceiling in various sectors such as residential and commercial. Its leading application segment is in the walls. The partitions and linings of the walls contain plasterboard because it also has soundproofing characteristic.
“The growing construction in the residential and commercial sector coupled with the on-going trend in which consumers from both the sectors have a palpable predilection for the soundproof walls will collective make the plasterboard market boom in the future,” highlights the market analyst in the plasterboard market research report. Furthermore, the analyst estimates the progression in the application CAGR of plasterboard in the walls segment to be 4.9% through to 2025.
Plasterboard Market Growth Drivers:
The Construction Industry Growth –
As mentioned earlier, the plasterboard market is predominantly making strides because of the growing construction industry. The construction industry is further segmented into commercial and residential –
The Population Growth Supporting the Real Estate Business –
By now, it’s discernible that there is a tangible upsurge in the world’s population, and it is only going to grow. This is bringing a seismic shift in the real estate sectors with the latest trend of smart homes which significantly make use of plasterboard.
As mentioned earlier, the plasterboard market is predominantly making strides because of the growing construction industry. The construction industry is further segmented into commercial and residential –
The Population Growth Supporting the Real Estate Business –
By now, it’s discernible that there is a tangible upsurge in the world’s population, and it is only going to grow. This is bringing a seismic shift in the real estate sectors with the latest trend of smart homes which significantly make use of plasterboard.
Inquiry Before Buying
Economic Growth and the Emergence of New Commercial Buildings –
The world is at the helm of economic progress, and most of the businesses now rely on technology which is leading to new projects in commercial buildings and complexes. Now, these buildings are incorporated with the plasterboard walls, which is further flourishing the plasterboard market.
Dry Construction Technique Gaining Prominence –
Dry Construction Technique (DCT) is 8-10 times lighter than the conventional brick construction technique and also enables 70% savings of the time which also helps the builders in to meet the targets in the turnaround time. Moreover, it reduces the use of water, thereby minimizing the impact of real estate on the environment. Now, this technique is becoming rampant in the real estate sector and leading to a remarkable growth in the demand for plasterboard.
Plasterboard Market Challenges:
The greatest challenge faced by the vendors in the plasterboard market is the fact that the old plasterboards need to be replaced by the new ones, and this is majorly attributed to their vulnerability to water contact. Now, due to the sporadic need for replacement, many customers prefer the conventional methods, and it gets difficult for the vendors to convince them about the advantage of plasterboards. However, the regular services offered by the vendors are making them overcome the challenge.
Dry Construction Technique (DCT) is 8-10 times lighter than the conventional brick construction technique and also enables 70% savings of the time which also helps the builders in to meet the targets in the turnaround time. Moreover, it reduces the use of water, thereby minimizing the impact of real estate on the environment. Now, this technique is becoming rampant in the real estate sector and leading to a remarkable growth in the demand for plasterboard.
Plasterboard Market Challenges:
The greatest challenge faced by the vendors in the plasterboard market is the fact that the old plasterboards need to be replaced by the new ones, and this is majorly attributed to their vulnerability to water contact. Now, due to the sporadic need for replacement, many customers prefer the conventional methods, and it gets difficult for the vendors to convince them about the advantage of plasterboards. However, the regular services offered by the vendors are making them overcome the challenge.
Schedule a call
Plasterboard Market Key Players Perspective:
The key players striving to capitalize on the demand influx in the plasterboard market are Armstrong World Industries Inc., Etex Group, Saint-Gobain SA, Georgia Pacific LLC, and Gypsum Management and Supply Inc.
Plasterboard Market Trends:
In October 2017, the gypsum wallboard and suspended ceilings distributor GMS Inc. acquired all the operating assets of Washing Builder’s Supply Company. This was attributed to GMS Inc.’s vision to position itself in the plasterboard market of Pennsylvania.
In January 2018, Etex had become the sole shareholder of Pladur which has plasterboard or gypsum wallboard plant near Madrid, and the company is building its second plant at Gelsa.
Plasterboard Market Research Scope:
The base year of the study is 2018, with forecast done up to 2025. The study presents a thorough analysis of the competitive landscape, taking into account the market shares of the leading companies. It also provides information on unit shipments. These provide the key market participants with the necessary business intelligence and help them understand the future of the plasterboard market. The assessment includes the forecast, an overview of the competitive structure, the market shares of the competitors, as well as the market trends, market demands, market drivers, market challenges, and product analysis.
In January 2018, Etex had become the sole shareholder of Pladur which has plasterboard or gypsum wallboard plant near Madrid, and the company is building its second plant at Gelsa.
Plasterboard Market Research Scope:
The base year of the study is 2018, with forecast done up to 2025. The study presents a thorough analysis of the competitive landscape, taking into account the market shares of the leading companies. It also provides information on unit shipments. These provide the key market participants with the necessary business intelligence and help them understand the future of the plasterboard market. The assessment includes the forecast, an overview of the competitive structure, the market shares of the competitors, as well as the market trends, market demands, market drivers, market challenges, and product analysis.
The market drivers and restraints have been assessed to fathom their impact over the forecast period. This report further identifies the key opportunities for growth while also detailing the key challenges and possible threats. The key areas of focus include the types of plasterboard market, and their specific applications in the walls, ceilings, and others. Moreover, the report also digs into the plasterboard’s applications in residential and commercial buildings and how it aids to the plasterboard market growth.
We also publish more than 100 reports every month in “Chemicals and Materials”, Go through the Domain if there are any other areas for which you would like to get a market research study.
Multilayer Aluminum Composite Pipes Market - Forecast(2020 - 2025)
Multilayer aluminum composite pipes comprises a composition of polyethylene, polypropylene, and other materials along with aluminum. These Pipes offer the advantages such as high strength and long durability as compared to conventional metallic or plastic pipes. Multilayer Aluminum Composite Pipes have many potential advantages over pipes made from conventional single material, which include high stiffness and strength, good corrosion resistance, light weight and improved thermal resistance properties.
The rapid growth of the construction, and electrical and electronics industries in Asian countries has given a huge boost to the global multilayer aluminum composite pipes market. The multilayer aluminum composite pipes market is estimated to grow at a CAGR of 5.7% during the forecast period 2019–2024.
Request Sample
Multilayer Aluminum Composite Pipes Market Outlook
The Multilayer aluminum composite pipes market has been categorized into various segments in the report. On the basis of manufacturing process, the market has been segmented into filament winding and rotary casting. Based on substrate, the market is segmented into (PE) and polypropylene (PP). The polyethylene segment is further sub-segmented into cross-linked polyethylene (PEX), high density polyethylene (HDPE), and others.
Based on end-user, the market is segmented into oil and gas industry, construction industry, chemical industry, electrical and electronics, telecommunications and others. The oil and gas industry is further sub-segmented into diesel and petrol, natural gas distribution and others; while construction industry is sub-segmented into residential, commercial and others. The chemical industry is further categorized into chemical processing and others; while electrical and electronics industry is sub-segmented into air conditioning, radiator central heating and others.
Multilayer Aluminum Composite Pipes Market Growth Drivers
Growing construction activities in Asian countries, with India being the front runner.
Increasing number of residential construction projects — Multilayer Aluminum Composite Pipes find major applications in plumbing.
Multilayer aluminum composite pipes are also used for chemical and gas Transportation. Increase in demand for natural gas for electricity production will automatically raise the demand for multilayer aluminum composite pipes.
Inquiry Before Buying
Multilayer Aluminum Composite Pipes Market Challenges
Raw materials account for nearly 60% of the overall cost of the multilayer aluminum composite pipes where aluminum and PE are the key raw materials for multilayer aluminum composite pipe. However, the rising prices of raw materials pose a major challenge for the growth of the multilayer aluminum composite pipes market. The price of aluminum has increased due to political events such as Rusal sanctions, US-China trade war while the PE prices are expected to witness an uptrend over the medium term.
Multilayer Aluminum Composite Pipes Market Share, By Country, 2018 (%)
Multilayer Aluminum Composite Pipes Market Research Scope
The base year of the study is 2018, with forecast done up to 2024. The study presents a thorough analysis of the competitive landscape, taking into account the market shares of the leading companies. These provide the key market participants with the necessary business intelligence and help them understand the future of the types of Multilayer aluminum composite pipes in the global Multilayer aluminum composite pipes market.
The assessment includes the forecast, an overview of the competitive structure, the market shares of the competitors, as well as the market trends, market demands, market drivers, market challenges, and product analysis. The market drivers and restraints have been assessed to fathom their impact over the forecast period. This report further identifies the key opportunities for growth while also detailing the key challenges and possible threats. The key areas of focus include the types of Multilayer aluminum composite pipes and its specific applications in the Multilayer aluminum composite pipes market.
Schedule a Call
Multilayer Aluminum Composite Pipes Market Report: Industry Coverage
Manufacturing Process of Multilayer Aluminum Composite Pipes: Filament Winding and Rotary Casting.
Substrate of Multilayer Aluminum Composite Pipes: Polyethylene and Polypropylene
End User of Multilayer Aluminum Composite Pipes: Oil and gas, Construction, Chemical, Electrical and electronics, Telecommunications, and Others
Multilayer Aluminum Composite Pipes Market Key Players Perspective
Uponor OYJ and Geberit are the two major manufacturers of multilayer aluminum composite pipes.Georg Fischer Ltd ,Geberit, Superpipe Middle East FZCO, Maincor Rohrsysteme Gmbh & Co.Kg and Kitec Industries are the some of the major companies in the multilayer aluminum composite pipes market.
Uponor OYJ, through its broad range of products, constant product launches, and innovation, has been successful in catering to a variety of customers. Monitoring its future business involvements, IndustryARC analysts expect Uponor OYJ to maintain its position in the market.
Multilayer Aluminum Composite Pipes Market Trends
Countries such as India and China have registered a significant growth of government infrastructural spending, increasing residential and commercial construction, industrial production, irrigation sector and replacement of aging pipelines. Further, the economic outlook for Asia-Pacific region is favorable owing to the large economic developments in China and India. All the major global major players have established their operations in this region. The increasing residential and commercial construction of Asia-Pacific, along with growing economic developments in the region, will drive the growth of multilayer aluminum composite pipes market.
Buy Now
We also publish more than 100 reports every month in “Chemicals and Materials”, Go through the Domain if there are any other areas for which you would like to get a market research study.

Surface Disinfectant Market - Forecast(2020 - 2025)
Surface Disinfectant Market size is $893m in 2019, growing at a CAGR of 8.7% during the forecast period 2020-2025. Surface Disinfectant are chemical substances that are applied to objects and surfaces for the purpose of sanitizing and killing microbes. It is used to disinfect food preparation surfaces, such as counter tops and cutting boards, owing to raw foods (meats, fish, and poultry) that contains pathogens like E. coli, Salmonella and Listeria.
Hydrogen Peroxide, Quaternary Ammonium, Hypochlorite and others are the type of surface disinfectants used to disinfect frequently touched surfaces in households, hospital acquired infections and others to reduce the transmission of infectious illnesses, such as COVID-19, colds, flu and others.
Request Sample
Key Takeaways
The increase of the prevention safety among the individuals in the medical and healthcare industry is set to propel the growth of the market.
Increasing consumer awareness about hygiene coupled with government initiatives promotes the Surface Disinfectant market.
Asia Pacific region is estimated to record the fastest growth rate during the forecast period 2020-2025.
By Product Type - Segment Analysis
In 2019, Hypochlorite segment dominated the Surface Disinfectant Market in terms of revenue is estimated to grow at a CAGR of 6.8%. It is the most common used type as it is available in solid (calcium hypochlorite) or liquid (sodium hypochlorite) forms. It is a bleaching product that is used in hospitals or private households all around the world to kill the germs or microorganisms which could spread the deadly virus like COVID-19 and others.
It is used in isolation wards and for sanitization purposes. As the number of sanitization processes are emerging around the world owing to the recent COVID-19 outbreak, the market is estimated to grow at an exponential rate.
Increasing consumer awareness about hygiene coupled with government initiatives promotes the Surface Disinfectant market.
Asia Pacific region is estimated to record the fastest growth rate during the forecast period 2020-2025.
By Product Type - Segment Analysis
In 2019, Hypochlorite segment dominated the Surface Disinfectant Market in terms of revenue is estimated to grow at a CAGR of 6.8%. It is the most common used type as it is available in solid (calcium hypochlorite) or liquid (sodium hypochlorite) forms. It is a bleaching product that is used in hospitals or private households all around the world to kill the germs or microorganisms which could spread the deadly virus like COVID-19 and others.
It is used in isolation wards and for sanitization purposes. As the number of sanitization processes are emerging around the world owing to the recent COVID-19 outbreak, the market is estimated to grow at an exponential rate.
Inquiry Before Buying
By Distribution Channel - Segment Analysis
In 2019, Online Retailing segment dominated the Surface Disinfectant Market in terms of revenue. It is owing to the enhancements and availability of varieties of surface disinfectant product in all types. Online retailing provides discount which attracts lot of individuals. People find it more useful as it makes purchase easy by giving comparison on the basis of its varieties, helps in saving time. Convenience and ease of availability of products aids in the growth of the market.
Geography - Segment Analysis
In 2019, the North America region dominated Surface Disinfectant Market in terms of revenue with a market share of 42%. Growth in the market is attributed to the efficient healthcare structure and the rising cases of COVID-19 which has led to an increase in the number of surface disinfectants.
As per claims of World Health Organization (WHO) the estimated statistics related to COVID-19 outbreak is 0.978 million, which would result in the growth of the market. Asia Pacific region is estimated to record the fasted growth rate during the forecast period 2020-2025.
Increase In Personal Hygiene
The growing demand for high quality surface disinfectants across the globe is owing to the increasing need to improve hygiene in hospitals, clinics, and ambulatory surgical centers to prevent the spread of infections (COVID-19) among patients and staff. Also the market is driven by the growing number of laboratories and the rising awareness among people about personal hygiene. The rising disposable incomes of people are the factors for the growth of the surface disinfectant market.
Challenges – Surface Disinfectant Market
The growing demand for high quality surface disinfectants across the globe is owing to the increasing need to improve hygiene in hospitals, clinics, and ambulatory surgical centers to prevent the spread of infections (COVID-19) among patients and staff. Also the market is driven by the growing number of laboratories and the rising awareness among people about personal hygiene. The rising disposable incomes of people are the factors for the growth of the surface disinfectant market.
Challenges – Surface Disinfectant Market
Heavy Adoption Of UV Radiation
The heavy adoption of UV radiation as a substitute for surface disinfectants is a major challenge for the market. Ultraviolet germicidal irradiation technique kills or restricts the effects of microorganisms by attacking their DNA and finishing the nucleic acids. The increased adoption of pre sterilization and practice of disinfecting medical instruments also act as major challenges for the surface disinfectant market.
Surface Disinfectant Industry Outlook
Product Launches was the key strategy of the players in the Surface Disinfectant Industry. Surface Disinfectant top 10 companies include 3M Company, CarroLLClean, Johnson & Johnson, The Clorox Company, The Procter & Gamble Company, Sealed Air Corporation, Whiteley Corporation, Metrex Research, LLC, STERIS Corporation and Cantel Medical Corporation.
Buy Now
The heavy adoption of UV radiation as a substitute for surface disinfectants is a major challenge for the market. Ultraviolet germicidal irradiation technique kills or restricts the effects of microorganisms by attacking their DNA and finishing the nucleic acids. The increased adoption of pre sterilization and practice of disinfecting medical instruments also act as major challenges for the surface disinfectant market.
Surface Disinfectant Industry Outlook
Product Launches was the key strategy of the players in the Surface Disinfectant Industry. Surface Disinfectant top 10 companies include 3M Company, CarroLLClean, Johnson & Johnson, The Clorox Company, The Procter & Gamble Company, Sealed Air Corporation, Whiteley Corporation, Metrex Research, LLC, STERIS Corporation and Cantel Medical Corporation.
Buy Now
We also publish more than 100 reports every month in “Lifesciences and Healthcare”, Go through the Domain if there are any other areas for which you would like to get a market research study.
Veterinary Vaccines Market - Forecast(2020 - 2025)
According to the findings by the International Federation for Animal Health, 61% of animal diseases are zoonotic, meaning they have the potential to cause human pandemics. Thus, veterinary vaccines are gaining traction as an imperative implementation for protecting animal health as well as public health as they effectively mimic the naturally acquired immunity. Increasing livestock population catering to feed the colossal non-vegetarian population coupled with the adoption of companion animals by the majority of households in developing as well as developed countries is disrupting the veterinary vaccines market.
Technological advancements in vaccines, increasing consciousness concerning animal health, increasing investments by government bodies and associations, and augmented demand for animal based protein has driven this arcade to reach a staggering market size of $7.5 billion as of 2018, and the demand is estimated to increment at formidable compound annual growth rate (CAGR) of 8.2% during the forecast period of 2019 to 2025.
Veterinary Vaccines Market Outlook:
Economic Relief by Veterinary Vaccines-
Apart from being zoonotic, animal contagious diseases have rampant tendency to ubiquitously disrupt the economic stability of livestock production. As per the Federation of American Scientists, an epidemic of mad-cow disease in England in the 1990s cost $9 billion - $14 billion as compensation to agrarians, and additional $2.4 billion from loss of export marketplaces.
As the livestock production accounts for nearly 40% of the global agricultural production value and is an integral source of nutrition for an estimated 9 billion population by 2050[3], veterinary vaccines market has found a major employer in this segment as animal diseases hamper efficient production and sources economic turbulence. Some of the transboundary animal diseases highly distressing the livestock sector commercial constancy are foot-and-mouth disease (FMD), H5N1 highly pathogenic avian influenza (HPAI), avian influenza (AI), lumpy skin disease (LSD), and Newcastle Disease.
After an acute analysis of the regional veterinary vaccines market share, North America was reckoned to be the dominating region securing the apex spot in terms of generating veterinary vaccines demand. This region accounts for 32% of the global veterinary vaccines market size as of 2018. The sheer affluence can be attributed to established vaccination programs and rise in ownership of pet animals. As per the National Pet Owners Survey conducted by the American Pet Products Association (APPA) 2017-2018, 68% of the U.S families own a pet with 60.2 million household housing a companion dog.
The United States Department of Agriculture (USDA) Center for Veterinary Biologics controls and authorize veterinary rabies vaccines. Some of the other canine vaccines include canine distemper, canine parvovirus, infectious canine hepatitis, adenovirus-2, leptospirosis, bordatella, canine parainfluenza virus, and Lyme disease. National Association of State Public Health Veterinarians, oversees vaccination and USDA-licensed vaccines. Thus, all these factor resonates the well-established veterinary healthcare facility disrupting the North America veterinary vaccines market growth.
There are several variants of vaccines designed for different kinds of diseases, such as veterinary viral vaccines, veterinary bacterial vaccines and veterinary parasite vaccines. Among these, live viral vaccines is the most dominant type flourishing at an application CAGR of 9.0% going through 2025. Live vaccines use an attenuated form of the germ that sources an infection. Owing to its peculiarities being identical to the natural contagion that they help in preventing, such vaccines create a resilient and enduring immune response. For instance, in 2017 Merck Animal Health pioneered the INNOVAX-ND-IBD, the first live vaccine curated with biotechnology that safeguards chickens from Newcastle Disease, transmittable bursal disease, and Marek’s ailment.
Veterinary Vaccines Market Trends and Growth Drivers:
Virus-like particle (VLP)-based vaccines- Some viral proteins can instinctively accumulate into biological nanoparticles, so-called ‘virus-like particles’. VLPs impersonates viral structures and are voluntarily acknowledged by the immune system, activating an enhanced immune reaction. Noticeable samples of VLP-based vaccines are some baculovirus/insect cell-expressed veterinary vaccines against Porcine circovirus 2 (PCV2), Ingelvac CircoFLEX® for example.
Modern developments in the study of virulence and pathogenicity amalgamated with operational molecular biological approaches have augmented the balanced design of vaccines, where virulence aspects have been controllably eradicated or functionally muted. This has headed to vaccines that uphold the useful properties of live vaccines while decreasing the threat for a possible reversion of virulence. A sample of this technology is a vaccine against Bovine viral diarrhoea virus (BVBD) recently introduced in the EU (Bovela).
Veterinary Vaccines Market Players Perspective:
Veterinary vaccines market is a flourishing arcade with players implementing biological and inorganic development policies to amplify their product offerings, reinforce their terrestrial spread, increase customer reach, increase substantial marketplace share and enhance veterinary vaccine development.
Some of the key players profiled in this report are Boehringer Ingelheim GmbH, Merck Animal Health, Zoetis Inc., Eli Lilly and Company, Bayer AG (Bayer Animal Health), Ceva Sant? Animale, Virbac, Biovac, Neogen Corporation, and ImmuCell Corporation.
December 2017, Prondil S.A., a developer and manufacturer of animal health vaccines for livestock was acquired by Merck Animal Health. This procurement aided Merck Animal Health to develop more progressive vaccines for a livestock animal in order to extend its market towards livestock sector.
Veterinary Vaccines Market Scope:
The base year of the study is 2018, with forecast done up to 2025. The study presents a thorough analysis of the competitive landscape, taking into account the market shares of the leading companies. It also provides information on unit shipments. These provide the key market participants with the necessary business intelligence and help them understand the future of the veterinary vaccines market.
The assessment includes the forecast, an overview of the competitive structure, the market shares of the competitors, as well as the market trends, market demands, market drivers, market challenges, and product analysis. The market drivers and restraints have been assessed to fathom their impact over the forecast period. This report further identifies the key opportunities for growth while also detailing the key challenges and possible threats. The key areas of focus include the various vaccines types in veterinary vaccines market, and their specific advantages.
We also publish more than 100 reports every month in “Lifesciences and Healthcare”, Go through the Domain if there are any other areas for which you would like to get a market research study.
Stents Market - Forecast(2020 - 2025)
The demand for stents is increasing to treat the diseases that affect the heart and blood vessels of elderly and middle-aged patients. Due to the current shift in the demographic structure caused by an aging society, the prospect for stents seems to be bright. A stent implant is commonly used for the treatment of cardiac abnormalities such as blocked blood vessels. They are also inserted in the ureter to prevent obstruction of urine flow from kidney, in the gall bladder to allow passage of bile in the patients suffering from the gall bladder cancer, and in the abdomen & gastrointestinal tract.
The Stents market is estimated to grow at a CAGR of 5.21% during the forecast period 2019-2024. Asia-Pacific is the fastest growing market with a CAGR of 8.13%, owing to the increasing number of patients with coronary artery diseases along with a significant decline in the prices of the stents and growing healthcare expenditure.
Stents Market Outlook
Stents are generally made of metals, polymers, and natural materials and are available for different clinical conditions in the market. The global stents market is estimated to witness significant growth during the forecast year due to increased incidence of heart-related diseases and huge demand for various diagnosis and treatment methods. Additionally, the increasing availability of diagnostic services for coronary heart diseases also fuels the growth of the market. Moreover, favorable reimbursement policies are likely to boost the market growth. The global stents market is analyzed to be dominated by the coronary stents with a share of 58% in 2018. The coronary stents market has recorded the revenue of US $6.73 billion in 2018 and expected to reach US $8.97 billion by 2024 with a CAGR of 5.2%. The major factors driving the growth of these stents include technological advancements and rising burden of cardiovascular diseases.
Stents Market Growth Drivers
There has been a significant increase in population with a cholesterol-rich diet and smoking habits since the last decade. The changing lifestyle and the growing millennial population with munching habits are resulting in high cholesterol intake. Moreover, the increase in the population of smokers is analyzed to add up the risk of atherosclerosis along with hypercholesterolemia. These habits and lifestyle changes are estimated to drive the stent market in the future as a significant share of the population with improper food and smoking habits would require coronary and peripheral angioplasty to re-open the blocked arteries.
Percutaneous Coronary Intervention (PCI) can be performed in a shorter interval of time than a bypass surgery as the stent is inserted into the body from the groin area or arm through a catheter. Owing to the lesser recovery and in-hospital time, stents has gained popularity among medical practitioners as well as patients. The adoption of stents for cardio vascular diseases is expected to grow at a healthy rate in the future owing to an increase in the demand for minimally invasive surgical procedures and reduction in surgery expenses.
Inquiry Before Buying
Stents Market Challenges
The stenting procedure involves certain risks despite its advantages over bypass surgeries. The risk of bleeding, bruises at the insertion point and in the artery lining remains at large followed by stent thrombosis (clotting of blood in the stent), allergic reactions to the dye or the stent, need for bypass surgery due to numerous blockages which cannot be treated by angioplasty and many others. This is analyzed to impede the adoption of stent and is poised to continue during the forecast period 2019-2024.
With the risks involved such as damage to the valves, stent thrombosis and many others there has been a significant increase in the regulation stringency involved in the production of the stent and also in the surgical methods used for placement and adjustment of the same. Moreover, extensive clinical trials are required to analyze the chances of allergic reactions with the stent material, coating, and contrasting dye before the product is commercially launched. Moreover the differences in the regional regulations also impedes the entry of the products into certain markets which increases the time to market the products thereby constraining its growth to a certain degree.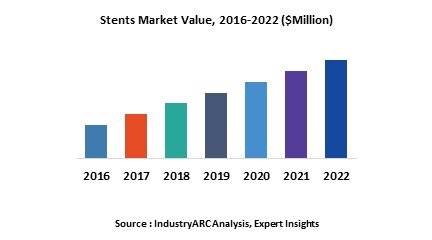
Stents Market Research Scope
The base year of the study is 2018, with forecast done up to 2024. The study presents a thorough analysis of the competitive landscape, taking into account the market shares of the leading companies. It also provides information on unit shipments. These provide the key market participants with the necessary business intelligence and help them understand the future of products that will be used in the stents market. The assessment includes the forecast, an overview of the competitive structure, the market shares of the competitors, as well as the market trends, market demands, market drivers, market challenges, and product analysis. The market drivers and restraints have been assessed to fathom their impact over the forecast period. This report further identifies the key opportunities for growth while also detailing the key challenges and possible threats. The key areas of focus include the type of product and material of stents.
Schedule a Call
Stents Market Report: Industry Coverage
By Product Type: Coronary, Peripheral, Carotid, Neurovascular, Biliary and others.
By Material: Metallic, Polymer, and Natural
The Stents market report also analyzes the major geographic regions for the market as well as the major countries for the market in these regions. The regions and countries covered in the study include:
Americas: The U.S., Canada, Mexico, Brazil and rest of Americas
Europe: The U.K., France, Italy, Germany, Spain, Russia, and Rest of Europe
APAC: China, Japan, South Korea, India, and Rest of APAC
RoW: Middle East and Africa
Stents Market Trends
Stenting is considered to be more comfortable than a bypass heart surgery for the heart patients. Stenting does not involve any major operation as it can be performed with the help of local anesthesia and low sedation, thus showing significant growth in the stent market.
The increase in chronic disease prevalence coupled with the rapidly aging population worldwide is set to increase demand for stent implants. According to the WHO report, in 2010 the population over the age of 65 was around 524 million, which is expected to grow to 1.5 billion by 2050.
Buy Now
We also publish more than 100 reports every month in “Lifesciences and Healthcare”, Go through the Domain if there are any other areas for which you would like to get a market research study.
